

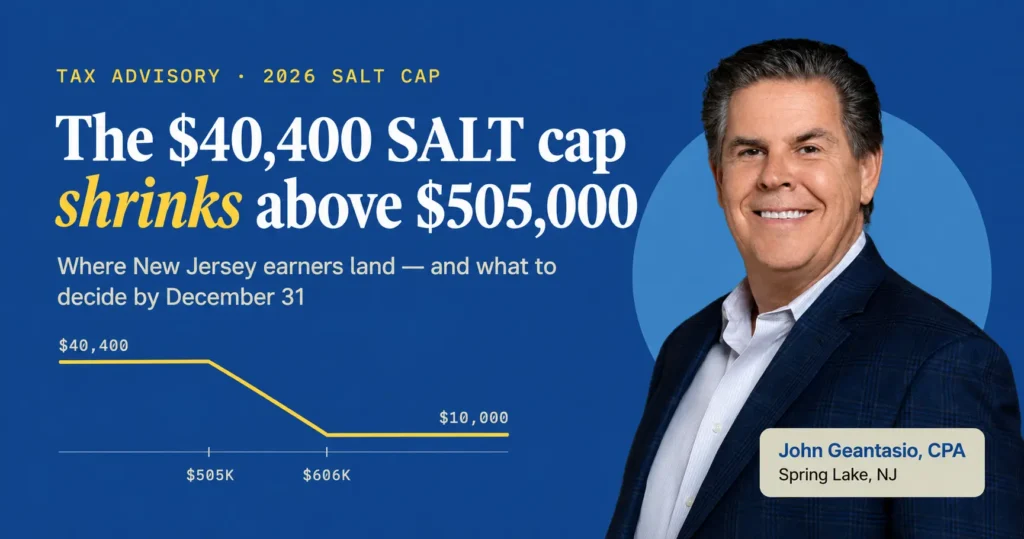
For 2026, the federal deduction for state and local taxes (SALT) is capped at $40,400 — but only while your modified adjusted gross income (MAGI) stays at or below $505,000. Above that line, the cap drops by 30 cents for every dollar of extra income until it reaches a $10,000 floor at about $606,333 of MAGI. The same thresholds apply whether you file single or jointly; married couples filing separately get half of each figure.
For New Jersey households, that band between $505,000 and $606,333 is where planning pays off most. A bonus, a business sale, a Roth conversion, or a large capital gain can move a household into, through, or out of it. The decisions that control where you land — retirement contributions, the timing of income, and a BAIT election for business owners — have to be made before December 31. This article walks through the rules, the math, and what to do at each income level.
What is the SALT cap in 2026, and who does it apply to?
The One Big Beautiful Bill Act (OBBBA), signed in July 2025, raised the SALT deduction cap from $10,000 to $40,000 for 2025. The cap and the income threshold both rise 1% a year through 2029:
- 2025: $40,000 cap (MAGI threshold $500,000)
- 2026: $40,400 cap (MAGI threshold $505,000)
- 2027–2029: 1% higher each year
- 2030 onward: $10,000 for everyone, unless Congress changes the law
Married couples filing separately get $20,200 each in 2026, with a $252,500 MAGI threshold and a $5,000 floor. The IRS confirms the 2026 figures in its 2026 Form 1040-ES correction notice.
Single filers and married couples filing jointly receive the same $40,400 cap and the same $505,000 threshold. A married couple does not get double the cap.
The SALT deduction counts only if you itemize. For 2026, the standard deduction is $32,200 for married couples filing jointly, $16,100 for single filers and married filing separately, and $24,150 for heads of household. If your mortgage interest, deductible state and local taxes, and charitable gifts together fall below your standard deduction, you take the standard deduction and the SALT cap has no effect on your return.
For most New Jersey homeowners with meaningful income, itemizing wins. New Jersey property taxes are among the highest in the country, and state income tax on a six-figure income adds up quickly. A Monmouth County couple earning $250,000 pays roughly $11,000 of New Jersey income tax; add a $12,000 property tax bill and their SALT alone is about $23,000. Mortgage interest of $9,200 or more carries them past the $32,200 standard deduction.
What counts as MAGI for the phaseout?
For most people, MAGI for this purpose is simply adjusted gross income (AGI) — the adjusted gross income line on your Form 1040. It adds back only a few items that rarely apply to New Jersey residents, such as the foreign earned income exclusion.
That matters because AGI is something you can influence. Pre-tax 401(k) contributions, HSA contributions, the timing of a capital gain, whether you convert to a Roth this year or next, and the structure of pass-through business income all change AGI — and therefore your SALT cap.
How does the phaseout reduce the deduction?
Once MAGI exceeds $505,000, the $40,400 cap is reduced by 30% of the excess. It never drops below $10,000 ($5,000 for married filing separately).
Couple with $560,000 MAGI in 2026. They are $55,000 over the threshold. 30% of $55,000 is $16,500. Their cap drops from $40,400 to $23,900.
Couple with $700,000 MAGI in 2026. They are $195,000 over the threshold. 30% of that is $58,500, which exceeds the $30,400 that sits above the floor. Their cap is $10,000 — the same limit that applied before the OBBBA.
The phaseout only costs you money if the state and local taxes you actually pay exceed your reduced cap. That is almost always true for a New Jersey household in this income range. Under New Jersey’s income tax rate schedules, a married couple with $560,000 of income owes roughly $31,000 to $33,000 of state income tax, depending on their New Jersey deductions. Add a property tax bill of $9,000 or more and the total passes $40,400. So in practice, for New Jersey residents in this band, every dollar of lost cap is a dollar of lost deduction.
At what income does the deduction fall all the way back to $10,000?
About $606,333 of MAGI in 2026 (single or joint). The math: the gap between the $40,400 cap and the $10,000 floor is $30,400. At a 30% reduction rate, it takes $101,333 of income above $505,000 to use up that gap. For married filing separately, the band runs from $252,500 to about $303,167.
That gives three zones:
- MAGI at or below $505,000: full $40,400 cap.
- MAGI between $505,000 and about $606,333: the cap shrinks by 30 cents per extra dollar of income.
- MAGI above about $606,333: $10,000 cap. The expanded SALT cap has no effect on your personal return.
What does the phaseout do to my real tax rate on extra income?
Inside the band, each extra dollar of income does two things: it is taxed at your regular bracket, and it removes 30 cents of SALT deduction. That lost deduction is itself taxed at your bracket.
For 2026, the federal brackets put most married couples in this band in the 32% bracket (taxable income over $403,550) or the 35% bracket (over $512,450). Single filers in the band are in the 35% bracket (over $256,225). In the 35% bracket, one extra dollar costs 35 cents of tax on the income plus 10.5 cents of tax on the lost deduction (30% of the 35% rate) — about 45.5 cents of federal tax per dollar. In the 32% bracket, the combined rate is about 41.6 cents. New Jersey income tax comes on top of that.
The phaseout is linear, so this higher rate applies evenly across the whole band — from the first dollar above $505,000 to the last dollar before $606,333. The same logic works in reverse: every dollar you keep out of MAGI inside the band saves you that same combined rate. That is why reducing MAGI inside the band is worth more than reducing it anywhere else.
Example. The couple at $560,000 MAGI each contributes an extra $10,000 of pre-tax money to their 401(k)s. The 2026 employee limit is $24,500 per person. MAGI drops to $540,000. Their SALT cap rises from $23,900 to $29,900. They avoid tax on the $20,000 they deferred and gain $6,000 of additional SALT deduction — between about $8,300 and $9,100 of federal tax saved, depending on whether that income comes out of the 32% or 35% bracket. The decision only requires a payroll change before the last paycheck of the year.
One caution for readers age 50 and over: starting in 2026, if your prior-year FICA wages from your employer exceeded $150,000, your 401(k) catch-up contributions must be made as Roth contributions. Roth contributions do not reduce MAGI, so for most people in this income band, only the regular $24,500 deferral works as a SALT lever.
Does New Jersey’s own tax return offer anything similar?
No. The $40,400 cap is a federal rule for Schedule A of Form 1040. It has no effect on your NJ-1040.
New Jersey does not allow a deduction for state and local income taxes. It offers a separate property tax deduction or credit on the state return: a deduction of up to $15,000 of property taxes paid on your principal residence, or a $50 refundable credit, whichever gives you the larger benefit. Renters can treat 18% of the rent they pay as property taxes for this purpose. That $15,000 limit does not change based on the federal SALT cap or your federal MAGI.
If I own a pass-through business, can BAIT get around the cap?
For income from an S corporation, partnership, or multi-member LLC taxed as either one, often yes — and it is the most valuable SALT planning tool available to New Jersey business owners. Single-member LLCs and sole proprietorships are not eligible.
New Jersey’s Pass-Through Business Alternative Income Tax (BAIT) lets the business elect to pay New Jersey tax on the owners’ share of business income at the entity level. The rates are 5.675% on the first $250,000, 6.52% from $250,001 to $1,000,000, and 10.9% above $1,000,000. Under IRS Notice 2020-75, the business deducts that tax on its federal return, and the payment is not counted against the owners’ SALT cap — or the $505,000 phaseout. Each owner then receives a refundable credit on their NJ-1040 for their share of the BAIT paid, so the total New Jersey tax paid stays roughly the same. The benefit is entirely on the federal side. The OBBBA left state pass-through entity taxes like BAIT in place.
BAIT also does something many owners overlook: because the business deducts the tax, the income passed through to the owner is lower, and so is the owner’s MAGI. That can move the owner down through the phaseout band and raise their personal SALT cap at the same time.
Example. The same couple at $560,000 MAGI, with $400,000 of that coming from their S corporation. With a BAIT election, the S corporation pays about $23,968 of BAIT (5.675% on the first $250,000 plus 6.52% on the next $150,000) and deducts it federally. Their pass-through income — and their MAGI — drops to about $536,000. Their personal SALT cap rises from $23,900 to about $31,100. And because the BAIT credit reduces the New Jersey income tax they owe personally, more of the tax they still pay personally fits under that higher cap.
Three rules decide whether BAIT works for a given year:
- The election is annual. It must be filed electronically by the original due date of the entity’s PTE-100 return — March 15 of the following year for a calendar-year business. Elections do not carry forward, and a return extension does not extend the election deadline.
- New Jersey will not accept BAIT payments until the election is on file. The entity has to elect before it can make estimated payments.
- The federal deduction follows the year of payment. Under IRS Notice 2020-75, the business deducts the BAIT in the year it pays it. An election filed in March 2027 for tax year 2026 is still valid for New Jersey, but a payment made in 2027 produces a 2027 federal deduction. The same applies to the fourth BAIT estimated payment, which is due January 15. To reduce 2026 federal income, the 2026 election must be on file and the payments made by December 31, 2026.
Should I itemize at all in 2026, or take the standard deduction?
Add up mortgage interest, your SALT deduction after any phaseout, and charitable gifts. If the total is below $32,200 (joint) or $16,100 (single), take the standard deduction.
If you are close to the line, bunching can help: concentrate two or three years of charitable gifts into one year — directly or through a donor-advised fund — so you itemize that year and take the standard deduction in the others. Starting in 2026, bunching carries an extra benefit. Itemizers can deduct charitable gifts only to the extent they exceed 0.5% of AGI each year, so concentrating gifts into one year means that floor applies once instead of several times. Households that take the standard deduction can now deduct up to $1,000 ($2,000 joint) of cash gifts made directly to charity — gifts to donor-advised funds do not qualify — which softens the cost of the off years.
Do other OBBBA rules reduce the value of my SALT deduction?
Two rules can, depending on your income and filing status.
The alternative minimum tax (AMT). State and local taxes are not deductible for AMT. For 2026, the AMT exemption is $90,100 for single filers and $140,200 for married couples filing jointly, and it begins phasing out at $500,000 and $1,000,000 of AMT income respectively. It now phases out at 50 cents per dollar, twice the old rate. For single filers, that means the AMT phaseout starts at nearly the same income level as the SALT phaseout. A single filer in the $505,000–$606,333 band can find that part of the SALT benefit is absorbed by AMT. For married couples in this band, the AMT threshold is far higher, so exposure is usually limited — though large incentive stock option exercises or capital gains can change that.
The new 35% ceiling on itemized deductions. Starting in 2026, taxpayers in the 37% bracket receive at most 35 cents of tax benefit per dollar of itemized deductions, including SALT. The 37% bracket begins at $768,700 of taxable income for married couples and $640,600 for single filers in 2026. Taxable income for anyone inside the SALT phaseout band is below those levels, so this rule only affects taxpayers who are already at the $10,000 SALT floor.
What happens to the SALT cap after 2029?
Under current law, the expanded cap runs from 2025 through 2029. In 2030 the cap returns to $10,000 for every taxpayer, regardless of income. That makes 2025–2029 a defined planning window: years to time property tax payments, structure BAIT elections, and schedule Roth conversions or asset sales with the higher cap in mind.
What to do before December 31, based on your income
If your 2026 MAGI will be well below $505,000: The full $40,400 cap is available. Confirm you are actually itemizing rather than defaulting to the standard deduction, and check whether bunching charitable gifts helps.
If your MAGI will land between about $475,000 and $606,333: This is the zone where year-end decisions have the largest effect. Before December 31:
- Project your 2026 MAGI with your full-year pay, bonuses, business income, and any gains realized so far.
- Maximize pre-tax 401(k) and HSA contributions if you have not already.
- Decide whether a planned Roth conversion or asset sale belongs in 2026 or a later year, based on where it puts you in the band.
- If you own a pass-through business, decide on a 2026 BAIT election now, so the election is on file and the payments are made before year-end.
- Single filers: model AMT alongside the SALT deduction.
If your MAGI will be above $606,333: The expanded cap does not help your personal return. Your main federal SALT lever is BAIT on pass-through business income. If your income sits just above the band, a large enough reduction — retirement contributions plus a BAIT deduction — can bring part of the cap back.
If most of your income is W-2 wages: Your levers are pre-tax retirement and HSA contributions and the timing of any investment income. BAIT is not available for wage income.
These decisions depend on one number: your projected 2026 MAGI. If you do not have that number yet, that is the first step — and it is the one we start with in a tax-planning consultation.
